Turn business assets into working capital.
AmeriCapital USA turns what you already own, like real estate, equipment, or receivables, into funding banks won't approve. No asset sale required, no minimum time in business.
What using your assets gets you that a bank loan doesn't.
Collateral changes the underwriting conversation. Here's what that means in practice.
Approval doesn't hinge on your credit score
Your collateral does the talking. A thin credit file or a rough year doesn't rule you out the way it would at a bank.
Keep the asset working for you
You borrow against equity instead of selling something that's still producing income or likely to appreciate.
A lower cost of capital
Collateral reduces our risk, and that usually shows up as a lower rate than unsecured financing.
Access to more capital
Asset-backed financing typically supports a higher approval amount than credit alone would allow.
Longer terms, smaller payments
Extended repayment schedules keep monthly obligations manageable for your cash flow.
Build credit while you borrow
On-time payments can strengthen your credit profile over time, the same as any other credit obligation you keep current.
No minimum time in business
Seasonal and newer businesses qualify. Approval isn't weighted on how long you've operated.
You likely have more borrowing power than you realize.
If it holds value, it can probably work as collateral. Here's what we finance against most often.
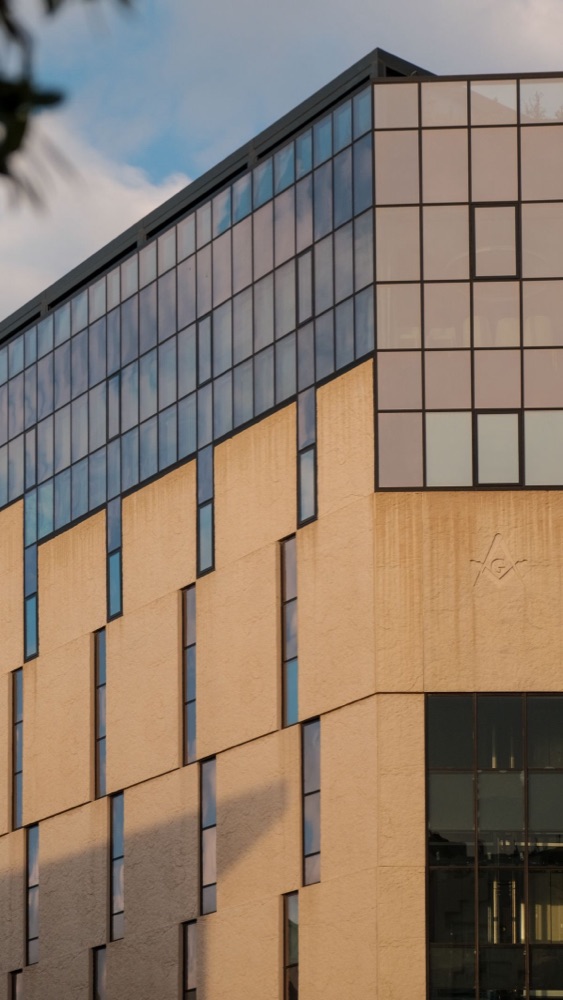
Commercial Real Estate
Offices, warehouses, industrial buildings, vacant land.
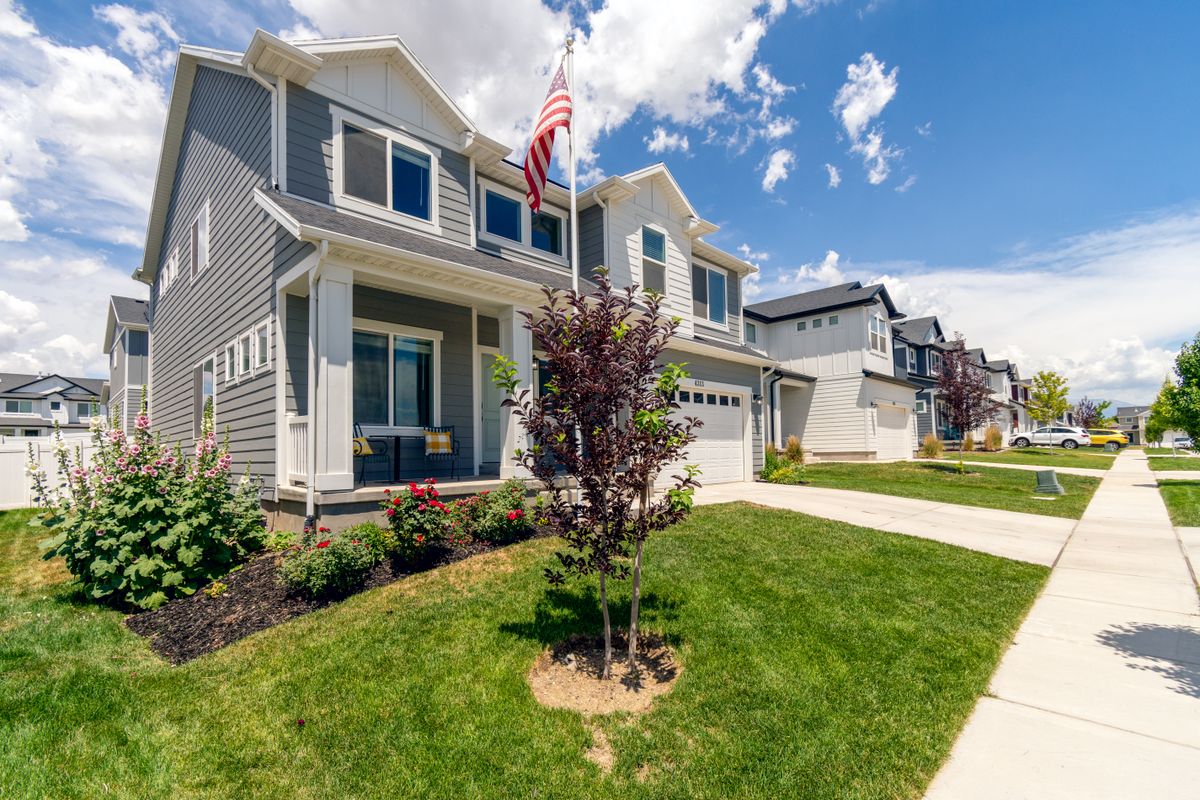
Residential Real Estate
Owner-occupied homes, investment and vacation properties, multifamily buildings.
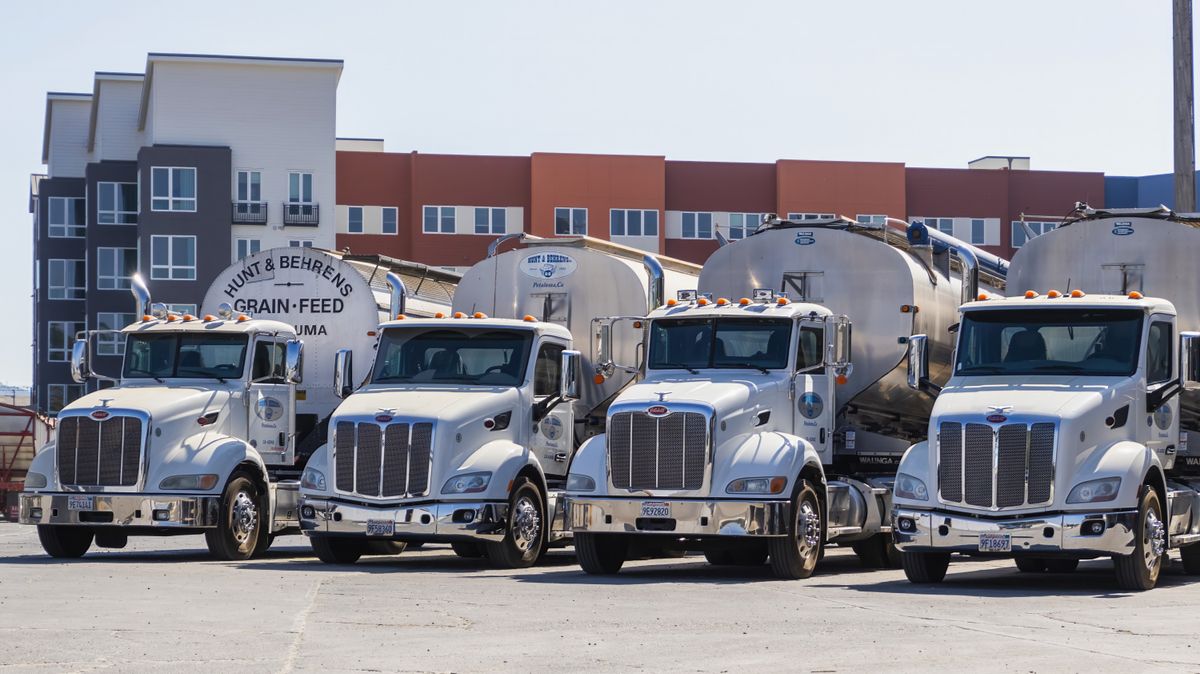
Business Assets & Equipment
Trucks, trailers, cranes, heavy machinery, aircraft.
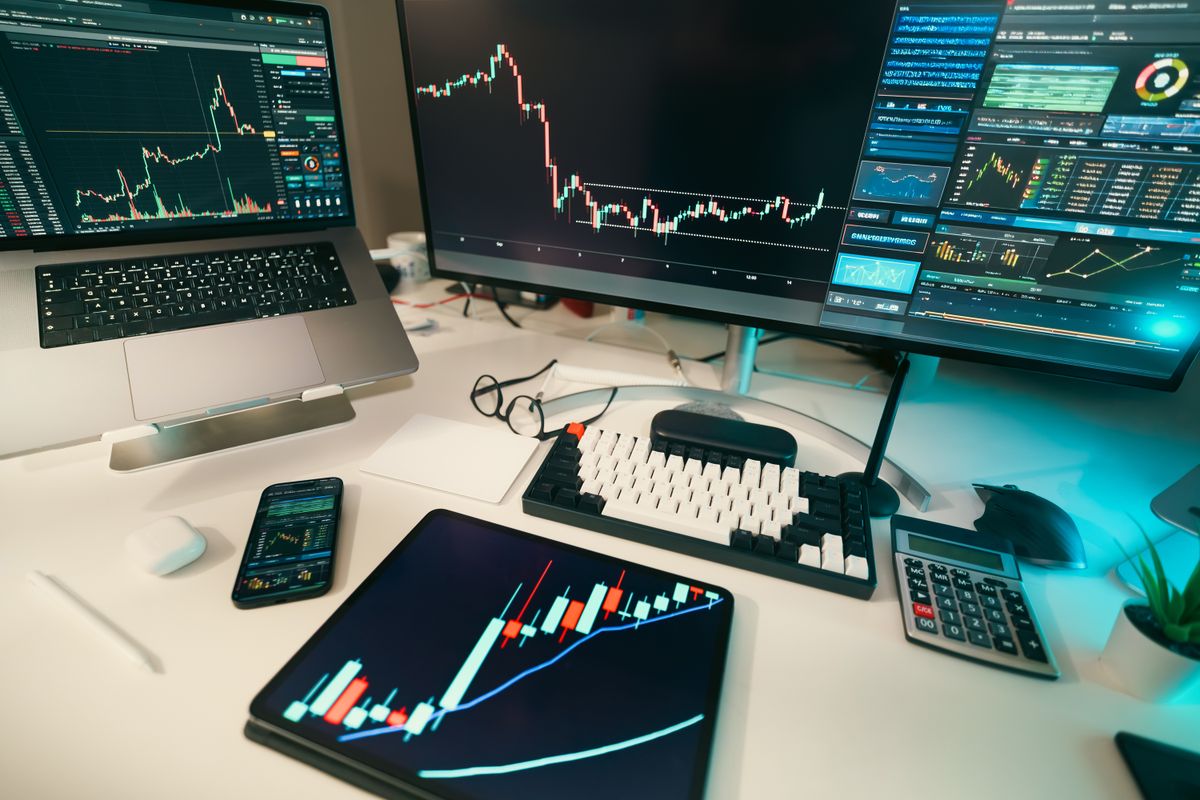
Financial Assets
Stocks, bonds, brokerage accounts, CDs, life insurance cash value.
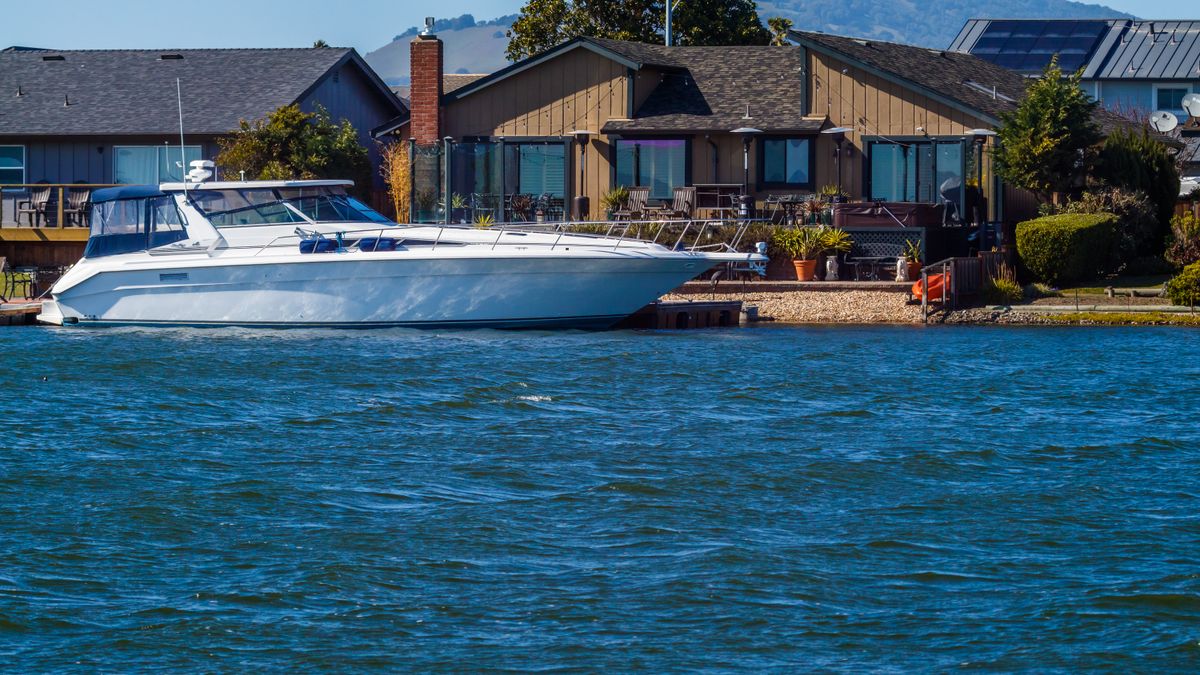
High-End & Luxury Assets
Boats, private aircraft, fine art, jewelry, collectibles, royalties and licensing rights.
Also eligible
- Inventory: finished goods and merchandise on your balance sheet
- Purchase Orders: confirmed orders waiting on funding to fulfill
- Accounts Receivable: 30 to 120+ day unpaid customer invoices
From asset to offer, in four steps.
- 1
Tell us what you need
Share the funding amount and which asset or assets you'd like to use.
- 2
We assess the asset
You'll get a one-page assessment, typically within a business day or two, outlining what's possible.
- 3
Review your offer
We walk through terms, structure, and cost together before anything is signed.
- 4
Get funded
Once you accept, funds typically move in days rather than the weeks a bank timeline takes.
Banks look at your credit.
We look at your assets.
| Traditional Bank | AMERICAPITAL USA | |
|---|---|---|
| Approval timeline | Weeks, sometimes longer | Days, not weeks |
| Credit requirements | Strict credit and time-in-business rules | Weighted on your asset, not your file |
| Income documentation | Extensive proof of income and cash flow | Asset value carries the underwriting |
| Loan amount | May fall short of what you need | Sized to the asset's real value |
| Underwriting style | Standardized boxes to fit into | A human review of your actual situation |
| Existing debt | Can work against your approval | Weighed in context, not as a dealbreaker |
| Funding speed | Delays even after approval | Typically released promptly after signing |
Approval timeline
Credit requirements
Income documentation
Loan amount
Underwriting style
Existing debt
Funding speed
Built for the industries banks underestimate.
Asset-heavy, cash-flow-seasonal, or newer businesses tend to get the least patience from traditional lenders.
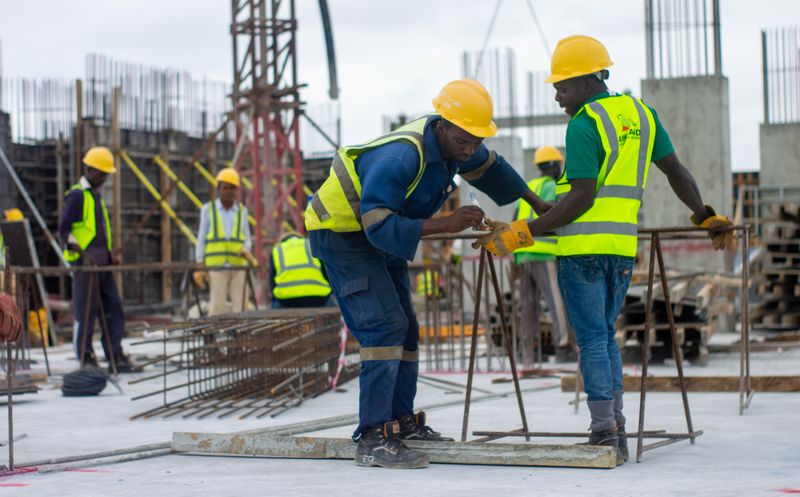
Construction
Project-based cash flow that rarely lines up with a bank's fixed repayment schedule.
Transportation & Trucking
Fleet-heavy balance sheets that carry real value banks tend to discount.
Manufacturing
Equipment and inventory tied up as capital instead of collateral.
Healthcare Practices
Long receivable cycles from insurers that strain short-term cash flow.
Real Estate Investors
Equity sitting in property that's slow to unlock through conventional refinancing.
Hospitality
Seasonal revenue swings that don't match a bank's time-in-business expectations.
The kind of outcome we aim for.
Representative client scenarios illustrating typical outcomes, shared for context, not verified endorsements.
“Banks kept asking for two more years of financials we didn't have. A lender in this space can look at the equipment instead and turn an offer around in days, not months.”
“A seasonal inventory buy doesn't wait for a 14-month-old business to build a credit history. Asset-backed financing was the option that didn't care how long the doors had been open.”
“Borrowing against the warehouse instead of selling it meant staying in control of the business through a tight quarter.”
Questions worth asking before you borrow.
It's financing secured by something you already own, like real estate, equipment, receivables, or financial assets, instead of relying only on your credit history. The asset's value carries much of the underwriting decision.
Ready to see what your assets can do?
Tell us the amount and the asset. We'll tell you what's possible, usually within a day or two.